When the IRS Sends a Letter: What to Do (and What Not to Do)
An IRS notice is not a verdict — it is a conversation. How you respond in the first ten days often determines how the entire matter resolves.
Tiffany Stimpson, EA
August 8, 2026
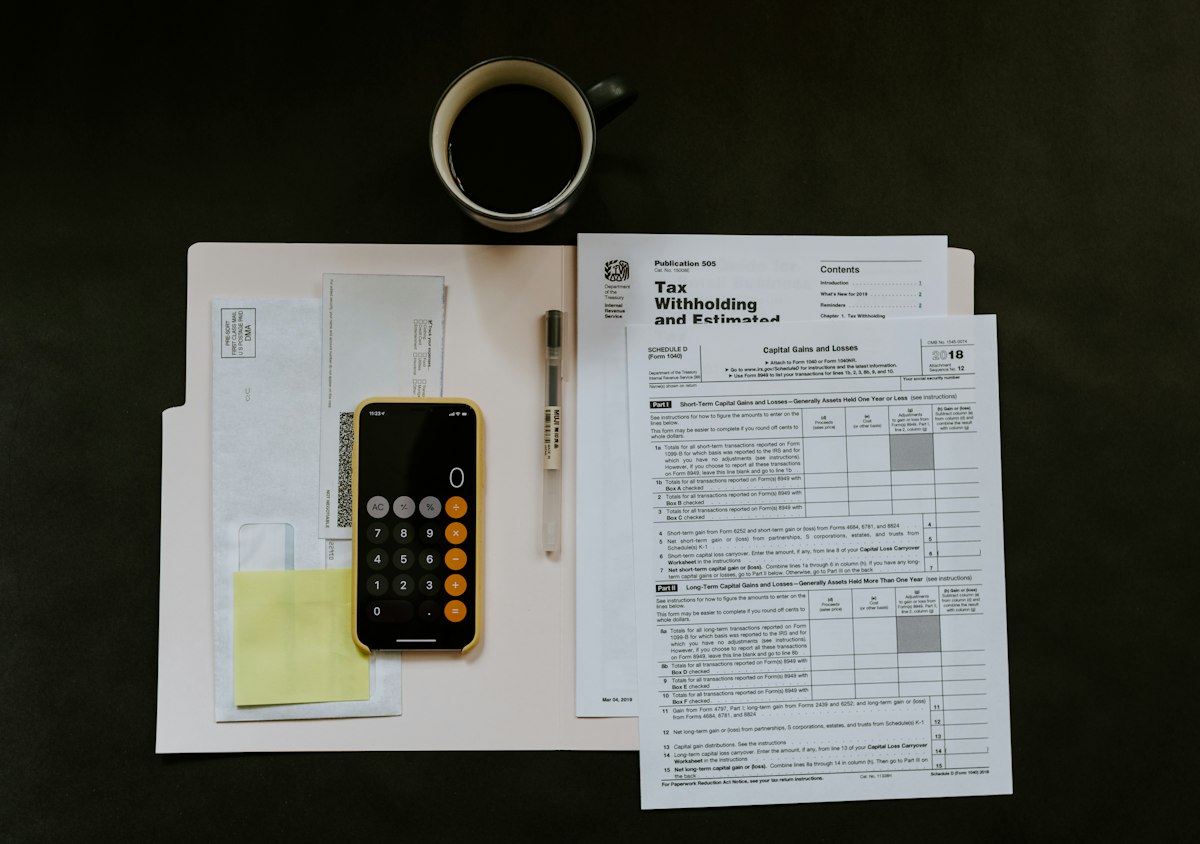
An envelope from the IRS has a way of stopping time. But the most important thing to understand about an IRS notice is this: a letter is not a judgment. It is the opening of a conversation.
How that conversation ends is shaped, more than anything, by how it begins.
Do not panic — and do not ignore it
The two most common mistakes are equal and opposite: reacting in fear, or setting the letter aside and hoping it resolves itself. Neither works. Notices carry response deadlines, and missed deadlines convert a manageable issue into a much larger one.
Do not call them yourself
When you call the IRS directly, every word you say becomes part of the record — and unguarded statements can be turned against a position you have not yet had the chance to define. This is the central case for representation: you speak through us, so your words can never be used against you.
Gather the documentation
Most IRS matters are resolved not by argument but by documentation. The moment a notice arrives, the work becomes organizing the records that support your position — returns, receipts, ledgers, correspondence. A well-documented file resolves faster and on better terms than an emotional one.
Understand what the notice actually says
Not every letter means you owe. Some are informational, some propose a change you can contest, and some begin a collection process that has multiple resolution paths — installment agreements, offers in compromise, penalty abatement. The right response depends entirely on which type of notice you hold.
The goal is never to win an argument with the IRS. The goal is to resolve the matter cleanly and restore your standing — with composure and authority.
If a letter has arrived, the first call to make is not to the IRS. It is to the person who will stand between you and them.